SIB Cashback Card
10% cashback online — up to 300 a month
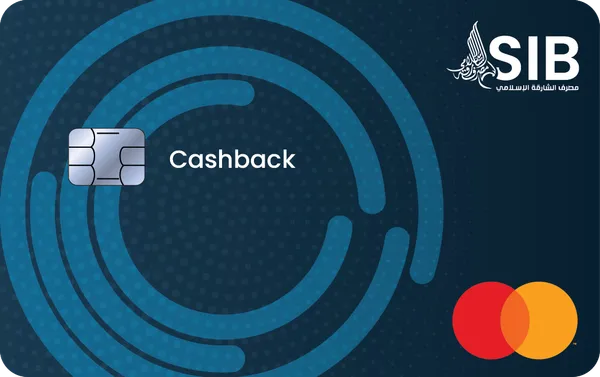
at Sharjah Islamic Bank's secure site
Terms and conditions apply. See rates & fees.
Cashback rate
"The 10% headline is genuine, and so is the 300 monthly ceiling behind it. Run roughly 3,000 of online and wallet spending through this card each month and you collect the maximum — around 3,600 a year from a card that is free in year one. Just don't carry a balance: 17 days of grace and 3.49% a month is an unforgiving combination."
Earning and redeeming SIB cashback
The card runs four rates. 10% on anything you buy online, with a card saved on a website or app, or through Apple Pay and Samsung Wallet — in the UAE or abroad. Then 2% uncapped on retail spending outside the UAE in foreign currency, 1% uncapped inside the UAE, and 0.5% on utilities, telecom, government, supermarket, hypermarket and education payments. The 10% tier is where the value sits and where the limit sits: 300 of cashback a month, which you reach at about 3,000 of qualifying spend. SIB's own worked example puts 9,000 of monthly spending at 370 back.
Redemption is deliberately simple and deliberately slow. Cashback is calculated when each statement is generated, and you can redeem once the balance reaches 100 — through SIB Digital or by calling the bank. It is credited against your outstanding balance, and SIB is explicit that this is not a payment: it will not offset the minimum you owe that month. Anything unredeemed expires 36 months after the transaction date.
Rates and fees
- Annual fee
- Free for the first year, then 199 (VAT inclusive) — waived if your retail spend in the previous year reached 10,000
- Cashback
- 10% online / wallet (capped at 300 a month), 2% international, 1% domestic, 0.5% on utilities, telecom, government, supermarket, hypermarket and education
- Monthly profit rate
- 3.49% Murabaha profit a month (41.88% a year) on the card limit — fully rebated as a bonus if you settle the statement in full by the due date
- Grace period
- Up to 17 days from the statement date
- Minimum payment
- 5% of the utilised amount, or 100 if higher
- Foreign currency
- 2.5% administration fee on non- transactions, excluding Mastercard's own fees — so the effective markup is higher
- Cash withdrawal
- Up to 80% of the card limit; fee of 3.5% of the amount (minimum 103.95)
- Late payment
- 236.25 'Commitment to Donate' — paid to charity, not to the bank
- Minimum salary
- 5,000 with salary transfer, 8,000 without. Minimum age 21.
- Supplementary cards
- Free — up to 4 for immediate family (spouse, parents, children, siblings)
- Card replacement
- 78.75; additional statement 47.25; copy of a purchase slip 68.25
- Card network
- Mastercard Titanium (covered card)
Rates verified against SIB's published Cashback Covered Card Key Facts Statement (English and Arabic) and sib.ae on 21 August 2026. All charges are stated by SIB as VAT inclusive. SIB's cards hub advertises a 3.15% cash withdrawal fee, which applies to the Smiles cards — the Cashback card's Key Facts Statement states 3.5%. Always confirm on SIB's site before applying.
Card benefits
10% online and wallet cashback
Online purchases, cards saved on websites and apps, Apple Pay and Samsung Wallet — in the UAE and abroad. Capped at 300 of cashback each month.
2% abroad, uncapped
Every foreign-currency retail purchase outside the UAE earns 2% with no ceiling — though a 2.5% FX admin fee applies on top of Mastercard's charge.
Free first year, waivable after
Nothing to pay in year one. From year two the 199 fee disappears if you spent 10,000 on retail purchases in the previous year.
Mastercard offers
Mastercard Priceless offers and up to 30% off hotel bookings through the Mastercard booking portal.
Serviced apartment and Hertz discounts
Discounted rates at selected luxury serviced apartments and Hertz Gold Plus Rewards five-star membership. SIB does not publish the discount levels.
Instalments and Easy Cash
Convert purchases to instalments over up to 12 months, transfer balances from other banks, or draw up to 80% of your limit as cash to any UAE account.
Pros and cons
- 10% on online, in-app and wallet spending is among the highest headline cashback rates published in the UAE
- The 2% international and 1% domestic rates carry no cap at all
- Free for the first year, and the 199 renewal is waived if you put 10,000 of retail spend through it
- Low entry bar — 5,000 salary with transfer, 8,000 without, and no minimum spend to start earning
- Sharia-compliant covered card: settle the statement in full and the bank rebates the profit, so you pay nothing
- The 10% rate stops at 300 of cashback a month — roughly 3,000 of qualifying spend
- Utilities, telecom, supermarkets, hypermarkets, government and education are cut out of the 10% and drop to 0.5%
- The grace period is only about 17 days from the statement date, where most UAE cards give 45–55
- 3.49% Murabaha profit a month (41.88% a year) if you don't settle in full
- A 2.5% foreign-currency admin fee sits on top of Mastercard's own charge, so the real cost abroad is higher than 2.5%
- Cashback only becomes redeemable at 100, is credited to the balance and never counts towards your minimum payment
Is it right for you?
Get this card if
- A big share of your spending is online, in apps, or through Apple Pay and Samsung Wallet.
- You settle your statement in full every month — the 17-day grace period leaves no room to drift.
- You want a cashback card you can get on an 5,000 salary with no minimum spend to qualify.
Consider skipping it if
- Your spending is concentrated in supermarkets, utilities or school fees — those categories drop to 0.5%.
- You expect to earn 10% on more than about 3,000 a month; the cap is a hard 300.
- You travel heavily and want cheap foreign spending — the 2.5% FX admin fee sits on top of Mastercard's own charge.
Alternatives to consider
ADIB's Cashback Gold is the other Islamic cashback covered card to weigh up — check whether its flat rates beat SIB's capped 10% for the way you actually spend.
Best cashback cards →
SIB's Smiles Titanium is free for life and turns the same spending into Smiles points for flights, hotels and vouchers instead of cash.
Best no-annual-fee cards →
For 525 a year the Smiles World adds unlimited airport lounge access, travel insurance and a 50,000-point welcome bonus — things the Cashback card has none of.
Best lounge access cards →Not sure which way to go? Put them side by side in our card comparison tool or browse the full ranked list.
Frequently asked questions
Do I need to register to receive cashback?+
No. You are automatically enrolled in the Cashback programme once you activate the card, and there is no minimum spend — every purchase transaction earns.
Do all online and wallet transactions earn 10%?+
Almost. All online and Apple Pay / Samsung Wallet transactions earn 10% whether they are made in the UAE or abroad, except utilities, telecom, supermarket, hypermarket, government and education payments — and the total is capped at AED 300 of cashback per month.
How much can I actually earn each month?+
The 10% category is capped at AED 300 a month, which you hit at roughly AED 3,000 of qualifying online spend. The 2% international and 1% domestic rates have no cap, and neither does the 0.5% bucket, so total monthly cashback can exceed AED 300.
How do I redeem my cashback?+
Cashback is calculated when your statement is generated. Once you have at least AED 100 you can redeem through SIB Digital online and mobile banking or by calling 065999999. It is credited against your outstanding balance — it is not treated as a payment, so it will not offset the minimum payment you owe.
What is the annual fee and how do I avoid it?+
The card is free for the first year. From the second year it is AED 199 (VAT inclusive), waived if your total retail spend in the previous year was AED 10,000 or more. Balance transfers, cash advances and fees don't count towards that AED 10,000.
When does my cashback expire?+
Cashback must be redeemed within 36 months of the date you made the transaction.
What salary do I need?+
AED 5,000 a month if you transfer your salary to SIB, or AED 8,000 a month if you don't. SIB also applies the Central Bank rules: minimum age 21 and a debt-burden ratio of no more than 50% of gross salary (30% for pensioners).
Is this card Sharia-compliant?+
Yes. It is a covered card built on a Bonds Murabaha contract combined with a Wakala investment account that holds your spending cover. The Murabaha profit is 3.49% a month (41.88% a year) on the card limit, but if you pay the full statement balance by the due date SIB credits the difference between the Murabaha and Wakala profit back as a bonus, so you pay nothing. The card cannot be used for non-Sharia-compliant purchases such as alcohol, pork, gambling or tobacco.
What happens if I pay late?+
SIB charges a 'Commitment to Donate' amount of AED 236.25, which goes to charity rather than to the bank — the Islamic equivalent of a late fee. Profit is then calculated daily on your utilised cover, and missed payments are reported to Al Etihad Credit Bureau.
Editorial disclaimer: Opinions expressed here are the author’s alone, not those of any bank or card issuer, and have not been reviewed, approved or otherwise endorsed by any of these entities.