ADCB Traveller Credit Card
2,000 Expedia.ae hotel voucher
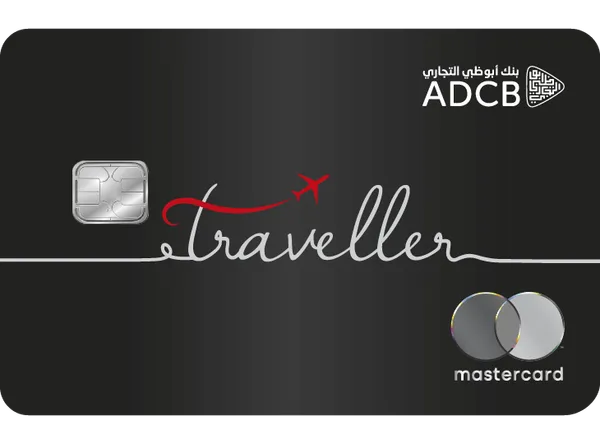
at ADCB's secure site
Pay the annual fee and spend 15,000 in 60 days. Terms apply. See rates & fees.
Cashback rate
"If your card spend clears 5,000 a month and you take even a couple of trips a year, the Traveller is close to unbeatable on travel: 10% off every flight and hotel plus zero FX fees compounds fast. Just be honest about the gate — in a quiet month it earns nothing, so pair it with a no-minimum everyday card rather than making it your only one."
Earning and using Traveller cashback
The headline rates are genuinely rich: 10% on airline tickets and hotel stays — any airline, any hotel, in or foreign currency — 50% on movie tickets bought online, and 1.5% on other domestic spend. Everything shares a 1,500 monthly cap, and the whole engine only switches on once you make 5,000 of retail spend in the calendar month (primary and supplementary cards combined). Miss the threshold and that month pays zero.
Cashback lands automatically in your card account the following statement — no portal, no vouchers, no minimum redemption. The catch to remember when abroad: international purchases outside flights and hotels earn no cashback, so the 0% foreign-currency fee is the card's only reward on overseas shopping and dining.
Rates and fees
- Annual fee
- 1,575 including VAT, charged from year one (bank-published figure — confirm on ADCB's fees page)
- Welcome offer
- 2,000 Expedia.ae hotel voucher on paying the annual fee and spending 15,000 within 60 days of issuance — once per customer lifetime
- Interest rate
- 3.25% per month on retail purchases; 3.50% per month on cash advances
- Interest-free period
- Up to 55 days when the balance is paid in full
- Foreign currency fee
- 0% foreign currency transaction margin
- Cash advance fee
- 3.15% of the amount, minimum 105
- Late payment fee
- 241.50; overlimit fee 288.75
- Minimum payment
- 5% of the outstanding balance or 100, whichever is higher
- Minimum salary
- 20,000 per month, or a credit limit of 30,000+; minimum age 21
- Card network
- Mastercard World Elite
Fee and interest figures are from ADCB's published Service & Price Guide (VAT-inclusive) and the bank's card page; ADCB last published the annual fee as 1,575 including VAT. Always confirm current rates on adcb.com before applying.
Card benefits
10% back on travel
10% cashback on airline tickets and hotel stays worldwide, in and foreign currency, up to 1,500 total cashback a month.
0% foreign currency fees
No bank processing fee on non- spend — one of the few UAE cards with a true 0% FX margin.
14 lounge visits a year
Access 1,200+ lounges via the Mastercard Travel Pass app, shared with supplementary cardholders, plus one free guest per visit.
Complimentary golf
Free rounds all year at Arabian Ranches Golf Club and Abu Dhabi Golf Club with 5,000 monthly card spend.
4 Careem airport rides
Four complimentary airport transfers a year (save up to 85 each) — pay in the Careem app with code MAUAE6.
GHA DISCOVERY Titanium
Titanium status at 500+ Global Hotel Alliance properties: upgrades, guaranteed availability, early check-in and late check-out.
Pros and cons
- 10% cashback on flights and hotels — in or any foreign currency — up to 1,500 a month
- 0% foreign currency transaction fee, rare in the UAE market
- 50% cashback on movie tickets booked online
- 14 lounge visits a year at 1,200+ lounges plus a free guest each visit
- Free golf, 4 Careem airport rides a year and GHA DISCOVERY Titanium hotel status
- Spend below 5,000 in a month and you earn no cashback at all
- International purchases outside airline and hotel bookings earn nothing
- 1,575 annual fee with no first-year waiver
- Base rate on everyday domestic spend is a modest 1.5%
- Lounge access needs a small non- transaction every 3 months to stay active
Is it right for you?
Get this card if
- You book flights and hotels a few times a year — 10% back in any currency beats every miles card on pure value.
- You reliably spend 5,000+ a month on cards and can route travel bookings here.
- You spend abroad often and want a genuine 0% foreign currency fee.
Consider skipping it if
- Your monthly card spend hovers near 5,000 — one quiet month and the card earns nothing.
- Most of your spending is everyday domestic shopping — 1.5% base is beatable by free cashback cards.
- You want rewards on international shopping and dining — only flights and hotels earn abroad.
Alternatives to consider
ADCB's everyday cashback card earns on regular spending without the Traveller's 5,000 monthly minimum and travel-only tilt.
Best cashback cards →
ADCB's TouchPoints flagship earns bank points you can redeem in-store, against your bill, or transfer to Skywards and Etihad Guest.
Best ADCB TouchPoints cards →
Committed Emirates flyers may squeeze more from Skywards Miles, Silver tier and lounge perks than from flat travel cashback.
Best Emirates Skywards cards →Not sure which way to go? Put them side by side in our card comparison tool or browse the full ranked list.
Frequently asked questions
What cashback does the ADCB Traveller Credit Card earn?+
10% on airline tickets (any airline, class or destination) and 10% on hotel stays worldwide, in AED and foreign currency; 50% on movie tickets purchased online in AED; and 1.5% on all other domestic AED spends. Cashback is capped at AED 1,500 per month.
Is there a minimum spend to earn cashback?+
Yes. You must make at least AED 5,000 of retail purchases on the card in a calendar month (primary plus supplementary cards combined) — below that, no cashback is earned on any spend that month.
Does the Traveller card charge foreign currency fees?+
No — the foreign currency transaction margin is 0%, so you pay no bank processing fee on overseas or non-AED spend. Note that international purchases other than flights and hotels don't earn cashback.
What is the annual fee on the ADCB Traveller card?+
AED 1,575 including VAT per the bank's published pricing, with no first-year waiver. ADCB's current page points to its fees and charges section for the latest figure, so confirm before applying.
What is the welcome offer?+
An AED 2,000 Expedia.ae hotel voucher when you pay the annual membership fee and spend AED 15,000 within 60 days of card issuance. The voucher is issued within 60 days of the fee payment, is valid for 6 months, works on hotel bookings at expedia.ae/adcb, and is offered once per customer lifetime.
Does the card include airport lounge access?+
Yes — 14 complimentary visits per year to more than 1,200 lounges worldwide via the Mastercard Travel Pass app, shared with supplementary cardholders, plus one free guest per visit (extra guests USD 32). After your first two visits, a non-AED transaction of at least USD 1 is needed to keep access active for 3 months at a time.
What is the minimum salary for the ADCB Traveller card?+
AED 20,000 per month, or eligibility for a credit limit of at least AED 30,000. You must also be at least 21 years old.
Editorial disclaimer: Opinions expressed here are the author’s alone, not those of any bank or card issuer, and have not been reviewed, approved or otherwise endorsed by any of these entities.