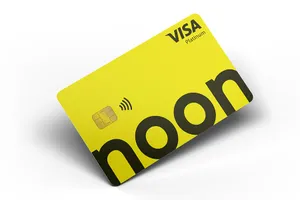
Mashreq noon Credit Card
5% back across the noon ecosystem
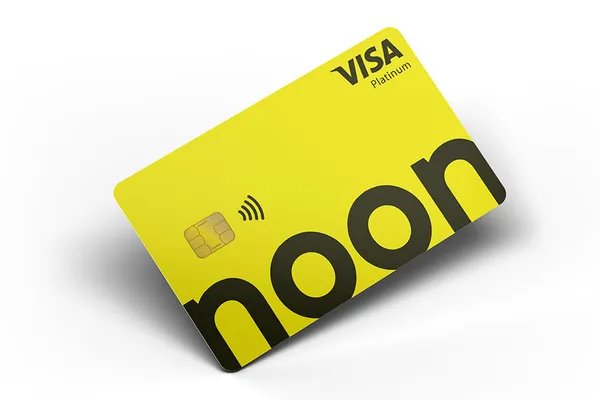
at Mashreq's secure site
Terms & conditions apply. See rates & fees.
Cashback rate
“Judge this card by one question: how often do you open the noon app? Weekly, and the 5% plus free express delivery beat anything else at zero fees. Rarely, and you're holding store credit that expires in a year — get the regular Cashback card instead.”
Earning and redeeming noon Credits
The earn structure is simple: 5% on noon, noon Food, noon Minutes, noon supermall, NowNow and Namshi, 1% everywhere else, and 0.33% on the usual penalty categories (government, utilities, education, charity, fuel, rent, telecom). There's no minimum spend — earning starts from the first — and cashback accrues on monthly spend up to your credit limit.
Here's what makes this card different from normal cashback: rewards are transferred monthly to your linked noon account as noon Credits, within 2 working days after your statement cycle, and are redeemed instantly at noon checkout or via noon Pay. They never touch your card balance, they can't be cashed out, and they expire 12 months after earning.
The welcome offer matches Mashreq's other cards: 500 for new Mashreq card customers ( 100 for existing ones) after 5,000 spend in the first 2 months.
Rates and fees
- Annual fee
- 0 — free for life, primary and supplementary cards; no joining fee
- Welcome bonus
- 500 (new customers) or 100 (existing) after 5,000 spend in 2 months
- Interest rate
- 3.85% per month (46.20% p.a. fixed) on unpaid balances
- Interest-free period
- Up to 57 days when the full balance is paid
- Minimum payment
- 5% of the monthly statement balance
- Minimum salary
- 5,000 per month
- Foreign transaction fee
- 2.89% on non- transactions (plus Visa scheme charges); 2.89% DCC on transactions abroad
- Cash advance fee
- 3.15% of the amount (minimum 210)
- Late payment fee
- 241.50
- Over-limit fee
- 303.45
- Card network
- Visa
Fees are VAT-inclusive as published in Mashreq's Key Facts Statement effective 13 June 2026; interest rates are VAT-exempt. Always confirm against the KFS before applying.
Card benefits
5% across noon
noon, noon Food, noon Minutes, noon supermall, NowNow and Namshi all earn 5% back as noon Credits, from the first .
Free express delivery
Automatic noon membership with unlimited free next-day delivery on noon express orders across the UAE.
500 welcome bonus
Spend 5,000 in your first 2 months as a new Mashreq card customer and get 500 back ( 100 for existing customers).
Instant digital card
A pre-activated digital card is issued the moment you're approved — shop on noon before the plastic ships.
Cinepolis 50% off
Half-price Deluxe-Plus seats at Cinepolis, up to 8 tickets a month, until 31 December 2026.
Free supplementary cards
Family cards cost nothing and their spending earns noon Credits into the primary account's linked noon ID.
Pros and cons
- 5% back across the whole noon ecosystem, with no minimum spend
- No annual fee ever, on primary and supplementary cards
- Unlimited free next-day noon express delivery
- Instant digital card issued at approval — no waiting for delivery
- Low 5,000 salary requirement
- Cashback lands as noon Credits, not cash — spendable only on noon platforms
- noon Credits expire just 12 months after earning
- Your noon account email is locked at application and can't be changed later
- Only 0.33% on government, utilities, fuel, rent and telecom; 1% elsewhere
- High 3.85% monthly interest (46.2% p.a.) and 2.89% FX markup
Is it right for you?
Get this card if
- You order from noon, noon Food or NowNow every week
- You want a zero-fee card and will actually spend the noon Credits
- You value free next-day delivery on noon express
- You want to start spending instantly with a digital card
Consider skipping it if
- You shop on noon only occasionally — credits expire in 12 months
- You want rewards as real cash against your card balance
- You spend heavily in foreign currency (2.89% FX markup)
- You want lounge access or any travel perks
Alternatives to consider
Emirates NBD's noon One is the direct rival — compare its noon Credit rates and perks before picking a side.
Best online shopping cards →
Same bank, same free-for-life deal, but cashback credits your card balance instead of a noon wallet — and dining earns 5%.
Best cashback cards →
Emirates Islamic's Cashback Plus delivers everyday cashback with an Islamic structure if that matters to you.
Best cashback cards →Not sure which way to go? Put them side by side in our card comparison tool or browse the full ranked list.
Frequently asked questions
What is the minimum salary for the Mashreq noon Credit Card?+
AED 5,000 per month, per Mashreq's card comparison table.
Does the Mashreq noon Credit Card have an annual fee?+
No — it is free for life, with no annual fee on primary or supplementary cards and no joining fee.
Where does my cashback go?+
Cashback accumulates monthly and is transferred to your linked noon account as noon Credits within 2 working days after your statement cycle. You can track it on the My Accounts page of your noon account.
How do I redeem noon Credits?+
Instantly at checkout on noon, noon Food, noon Minutes and other noon platforms (web and app), including via noon Pay.
Does the cashback expire?+
Yes — noon Credits earned from the card are valid for 12 months from the date of earning. Unredeemed credits expire after that.
Do I become a noon Member with this card?+
Yes, you automatically become a noon Member the day after your card is activated, which includes free next-day delivery on noon express orders.
Which transactions don't earn cashback?+
Easy Cash, balance transfers, cash advances, credit card cheques, finance charges, bank fees, reversed transactions, and utility bill payments made through Mashreq's own channels. Cashback also only accrues on monthly spend up to your assigned credit limit.
Do I need a noon account to apply?+
You provide a noon account email during digital onboarding. If you don't have a noon account, noon emails you to create one — but the email cannot be changed after the application is submitted.
Editorial disclaimer: Opinions expressed here are the author’s alone, not those of any bank or card issuer, and have not been reviewed, approved or otherwise endorsed by any of these entities.