Emirates NBD WebShopper
A sealed-off card for online shopping
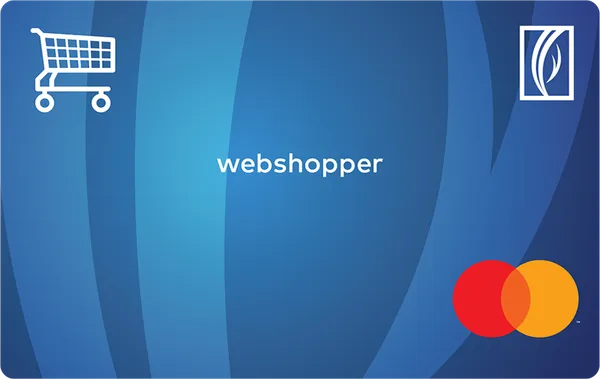
at Emirates NBD's secure site
Terms & conditions apply. See rates & fees.
Rewards rate
"The WebShopper answers one question well: how do I shop online without exposing my main card? It can't be swiped, inserted or used at an ATM, so a leaked number stays contained. Whether that's worth 52.50 a year in the age of free virtual card numbers is the real question — the 1-point-per--200 'rewards' certainly aren't the reason."
Earning and redeeming Plus Points
There is not much to say, and that is the honest summary: the WebShopper earns 1 Plus Point per 200 spent — a fraction of what even Emirates NBD's free cards earn — and it earns only online, because that is the only place the card works.
Points land in the same Plus Points programme as the bank's other cards and are redeemed through Emirates NBD's usual redemption channels. Treat any points as a rounding error; you buy this card for the containment, the up-to-55-day interest-free period and the big-ticket purchase insurance, not the earn rate.
Rates and fees
- Joining fee
- 52.50, VAT inclusive
- Annual fee
- 52.50 per year, VAT inclusive
- Interest rate
- 3.69% per month (44.28% p.a.) on unpaid balances; 3.25% for UAE nationals
- Interest-free period
- Up to 55 days on retail purchases and related fees and charges
- Minimum payment
- 5% of the outstanding balance or 100, whichever is higher
- Minimum salary
- 5,000 per month
- Foreign transaction fee
- 1.99% bank fee plus ~1.15% network processing fee — applies to international websites billing in foreign currency
- Cash advance
- Not possible — the card cannot be used at ATMs
- Late payment fee
- 241.50 per month
- Card network
- Mastercard (online-only)
Rates verified against Emirates NBD's Key Facts Statement (08/2026) and credit-card price guide (Feb 2026), both VAT-inclusive. Always confirm on the issuer's site before applying.
Card benefits
Online-only by design
The card number is printed, not embossed — it cannot be swiped, inserted into a terminal or used at an ATM, so a leaked number does limited damage.
Big-ticket purchase insurance
Complimentary insurance cover for big-ticket purchases made on the card.
Works on any online store
Use it on local and international websites — foreign-currency purchases carry the standard ~3.1% combined FX fees.
A token of Plus Points
1 Plus Point per 200 spent, redeemable through Emirates NBD's Plus Points channels.
Pros and cons
- Purpose-built security: the card physically cannot be used at POS terminals or ATMs, containing the damage if it leaks
- Cheap to hold at 52.50 a year (VAT inclusive)
- Complimentary insurance cover for big-ticket purchases
- Accessible 5,000 minimum salary
- Up to 55 days interest-free and 0% instalment plans at participating merchants
- Near-zero rewards — 1 Plus Point per 200 spent
- Cannot be used in stores, at ATMs, or anywhere requiring the physical card
- 1.99% foreign-transaction fee plus a ~1.15% network fee — and much online shopping is billed in foreign currency
- High 3.69% monthly interest rate (44.28% p.a.)
- Virtual-card numbers and card controls on ordinary cards now solve most of the same problem for free
Is it right for you?
Get this card if
- You want a physically separate card for online spending with its own limit and contained risk.
- You shop on sites you don't fully trust and want your main card kept out of it.
- You earn 5,000+ and are fine paying 52.50 a year for that separation.
Consider skipping it if
- Your bank already gives you free virtual card numbers and per-channel card controls — they do the same job for nothing.
- You want rewards on online shopping — 1 point per 200 is effectively zero, and dedicated online-shopping cards earn many times more.
- You shop mostly on international sites — the ~3.1% combined FX cost wipes out any convenience.
Alternatives to consider
A free card built around noon's ecosystem that actually pays you back on online spending.
Best online shopping cards →
Free under the current offer at the same 5,000 salary, works everywhere, and still earns more than the WebShopper.
Best no-annual-fee cards →Not sure which way to go? Put them side by side in our card comparison tool or browse the full ranked list.
Frequently asked questions
Where can I use the WebShopper card?+
Only for online transactions. The card number is printed rather than embossed, so it cannot be used at merchants that require swiping or inserting the card into a terminal, nor at ATMs to withdraw cash.
What are the WebShopper card's fees?+
AED 52.50 joining fee and AED 52.50 annual fee, both inclusive of VAT. The interest rate is 3.69% per month, and the minimum payment is 5% of the outstanding balance or AED 100, whichever is higher.
What is the minimum salary for the WebShopper card?+
AED 5,000 per month.
Does the WebShopper card earn rewards?+
Barely — 1 Plus Point for every AED 200 spent. It is a security product, not a rewards card.
Is there an interest-free period?+
Yes — up to 55 days on retail purchases and related fees and charges, provided you pay the balance in full by the due date.
Do foreign-currency fees apply to online purchases?+
Yes. Purchases from international websites billed in foreign currency incur a 1.99% currency conversion fee plus the card network's processing fee of approximately 1.15%.
Editorial disclaimer: Opinions expressed here are the author’s alone, not those of any bank or card issuer, and have not been reviewed, approved or otherwise endorsed by any of these entities.