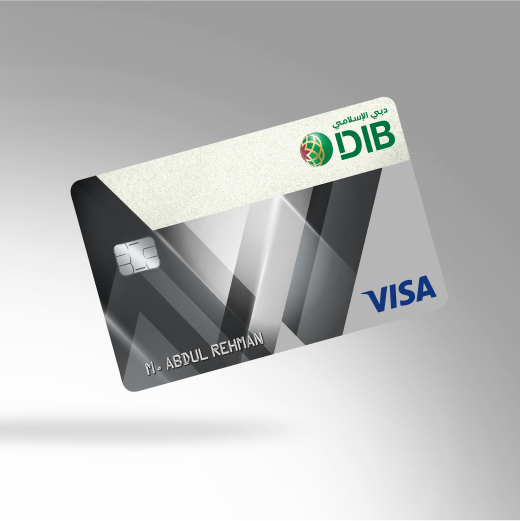
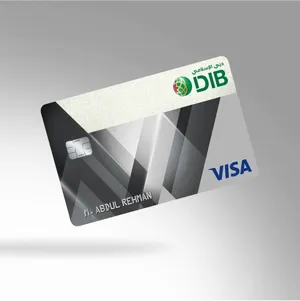
DIB Prime Gold Card
A Sharia-compliant card that's free for life
at Dubai Islamic Bank's secure site
Terms & conditions apply. See rates & fees.
Rewards rate
"The Prime Gold does exactly what a free Islamic starter card should: no fee ever, real travel takaful, roadside assistance — and it never pretends to be a rewards powerhouse. At 0.2 Wala'a per on essentials and 3.70% on foreign spend, treat the points as a rounding error, not a reason to apply."
Earning and redeeming Wala'a Rewards
The card earns 0.6 Wala'a Rewards per 1 on retail spend in the UAE and 1 Wala'a per 1 equivalent in foreign currency. The fine print matters: supermarkets, telecom, education, petrol, government services (including utility bills), takaful, car dealers, transport and real estate earn just 0.2 per , retail spend originating in EU countries earns nothing, and bills paid through DIB's own platforms, charity, crypto, wire transfers and similar quasi-cash transactions are excluded entirely.
Redemption is flexible for a free card: Wala'a Rewards can go toward flight tickets, hotel stays, retail purchases and bill payments. DIB doesn't publish a fixed value per Wala'a, and the rewards do expire — check the Wala'a Rewards terms before you stockpile.
Rates and fees
- Annual fee
- Free for life — no annual or renewal fee in DIB's Schedule of Charges (Aug 2026)
- Profit rate
- Up to 3.69% per month (Salam-based monthly rate) on unsettled balances — no interest is charged
- Minimum salary
- 5,000 per month
- International usage fee
- 3.70% on non- transactions; 3.14% even on -denominated transactions processed abroad
- Cash withdrawal fee
- 3.15% of the transaction amount; withdrawal limit up to 80% of your card limit
- Late payment
- 236.25 charity donation per instance (routed to charity under Sharia supervision, not a bank fee)
- Minimum payment
- 5% of the principal balance or 100, whichever is higher
- Supplementary cards
- Free
- Credit Shield Takaful
- Optional, 0.94% of outstanding per month — covers death ( 200,000), permanent disability ( 200,000) and job loss ( 30,000)
Rates verified against DIB's Schedule of Charges for cards (effective 11 August 2026) and the DIB Covered Cards Key Facts Statement (Aug 2026); all amounts include 5% VAT. Always confirm on dib.ae before applying.
Card benefits
US$ 75,000 travel takaful
Travel and medical coverage up to US$ 75,000 when you book flights on the card — for you, your spouse and up to 4 children under 18.
Credit Shield Takaful
Optional cover at 0.94% of the outstanding per month: 200,000 for death or permanent total disability, 30,000 for involuntary job loss.
Roadside assistance
Complimentary roadside assistance up to twice a year — towing, battery boost, flat tyre, fuel delivery, off-road pull-out — plus 75% off an international driving licence.
Cash flexibility
Withdraw up to 80% of your card limit in cash and transfer cash from the card straight to your DIB account.
Balance transfer facility
Move 100 to 250,000 of other banks' card balances — up to 80% of your limit — via online or mobile banking, no documents needed.
Card Protection Plus
Optional security controls: set transaction types, spending limits and location restrictions on your card.
Pros and cons
- Genuinely free for life — the Schedule of Charges lists no annual or renewal fee for any Prime card
- Accessible 5,000 minimum salary
- Fully Sharia-compliant Salam-based covered card; late payment is a charity donation, not bank income
- Travel and medical takaful cover up to US$ 75,000 when you book flights on the card
- Complimentary roadside assistance twice a year, plus 75% off an international driving licence
- Essentials earn a token 0.2 Wala'a per — supermarkets, fuel, telecom, education, utilities and more
- High 3.70% international usage fee on non- spend (plus 3.14% even on -denominated foreign transactions)
- No airport lounge access or premium travel perks
- EU retail spend earns nothing, and DIB doesn't publish a clear value for Wala'a Rewards
- Up to 3.69% monthly Salam profit rate if you don't settle in full
Is it right for you?
Get this card if
- You want a Sharia-compliant card with no annual fee — ever — at an 5,000 salary.
- You book flights on your card and value the US$ 75,000 travel takaful cover.
- You drive: free roadside assistance twice a year is a genuinely useful perk.
Consider skipping it if
- Your spending is mostly groceries, fuel, telecom or school fees — those earn a token 0.2 Wala'a per .
- You travel or shop in foreign currency often — the 3.70% international usage fee outweighs the earning.
- You want lounge access or premium perks — look at DIB's SHAMS or Skywards cards instead.
Alternatives to consider
Also fee-free, with hotel privileges and stronger travel extras one tier up.
Best no-annual-fee cards →
3% guaranteed cashback on supermarkets, fuel, bills and school fees at the same 5,000 salary.
Best cashback cards →
DIB's SHAMS Platinum adds lifestyle perks and stronger Wala'a earning for a modest annual fee.
Best Islamic cards →Not sure which way to go? Put them side by side in our card comparison tool or browse the full ranked list.
Frequently asked questions
Does the DIB Prime Gold Card have an annual fee?+
No. DIB's Schedule of Charges (effective August 2026) lists the annual and renewal fee for all Prime covered cards as free — not just for the first year.
What is the minimum salary for the Prime Gold Card?+
AED 5,000 per month, as stated on DIB's card page.
How do Wala'a Rewards work on this card?+
You earn 0.6 Wala'a Rewards per AED 1 on retail spend and 1 Wala'a per AED 1 equivalent in foreign currency. Supermarkets, telecom, education, petrol, government services, takaful, car dealers, transport and real estate earn a reduced 0.2 per AED 1, and EU-originated spend earns nothing. Redeem for flights, hotels, retail purchases and bill payments.
Is the Prime Gold Card Sharia-compliant?+
Yes. DIB is a fully Islamic bank and its covered cards are structured on the Sharia principle of Salam, approved by the bank's Internal Sharia Supervision Committee. There is no interest — the bank earns a profit rate, and late payers commit to a charity donation (AED 236.25) rather than paying a penalty fee to the bank.
What happens if I pay late?+
You undertake to donate AED 236.25 per instance, which DIB routes to designated charities under the supervision of its Sharia committee after deducting actual collection costs. A late payment can also hurt your Al Etihad Credit Bureau rating.
Does the card include travel insurance?+
Yes — travel and medical coverage up to US$ 75,000 when you book your flight tickets with the card, covering you, your spouse and up to four children under 18.
Can I transfer balances from other cards?+
Yes. The balance transfer facility lets you move up to 80% of your card limit (or 100% of the available cash limit), minimum AED 100 and maximum AED 250,000, via online or mobile banking with no documentation.
Editorial disclaimer: Opinions expressed here are the author’s alone, not those of any bank or card issuer, and have not been reviewed, approved or otherwise endorsed by any of these entities.