Al Hilal Bank Cashback Credit Card
5% cashback on two categories you choose
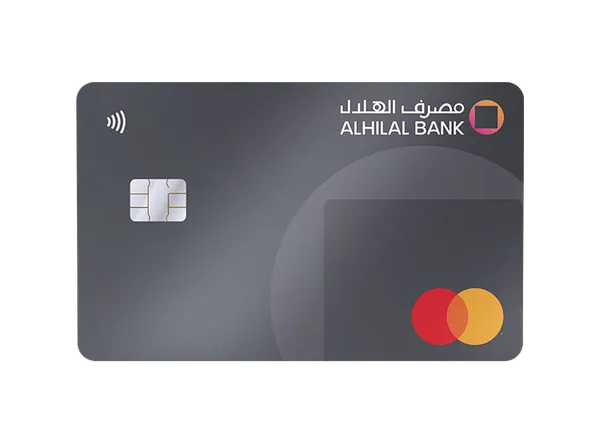
via the Al Hilal Bank app
Sharia-compliant covered card. Terms apply. See rates & fees.
Cashback rate
For a card that costs nothing, letting you point 5% at your two biggest spending categories is a strong deal - but treat the 8,000 monthly spend tier as the real price of admission. If your card spend is lighter than that, you're holding a 1% card with a lounge perk.
Earning and receiving your cashback
You pick two 5% categories in the Al Hilal app from grocery, fuel, dining, education and international spend, and can change them monthly (free twice a calendar year, 25 after that). The 5% is tiered by your total monthly retail spend: over 8,000 unlocks the full 5%, 3,000-8,000 pays 3%, and below 3,000 your chosen categories earn the same 1% as everything else.
Each chosen category is capped at 250 a month and total cashback at 500. The month's cashback lands on your card account by the 15th of the following month - automatically, with nothing to redeem. Watch the exclusions: government-type payments and utility bills paid in the app earn 0%, EEA merchants earn 1% even on the international category, and you must pay at least the minimum due to keep that month's cashback.
Rates and fees
- Annual fee
- Free for life - no joining fee, up to 3 free supplementary cards ( 105 from the 4th)
- Profit rate (Murabaha)
- 3.69% per month (44.28% p.a.) for new customers; 3.25% for cards issued before 2024
- Profit-free period
- Up to 55 days on retail transactions when the balance is paid in full
- Foreign transaction fee
- 3.14% - also applies to transactions made outside the UAE
- Cash withdrawal
- 3.15% of the amount; withdrawal limit 60% of the card limit
- Late payment
- 100 'Commitment to Donate' (given to charity) - waived if the minimum due is paid on time
- Minimum payment
- 5% of the statement balance or 100, whichever is higher
- Cashback category change
- Free twice per calendar year, 25 for the 3rd change onwards
All charges include VAT. Rates from Al Hilal Bank's Schedule of Fees (V3.7, June 2026) and Key Facts Statement (March 2026); confirm on the bank's site before applying.
Card benefits
Pick-your-own 5% categories
Choose any two of grocery, fuel, dining, education and international spend for 5% cashback, and reshuffle monthly from the app as your spending changes.
Airport lounge access
25+ lounges including Marhaba and CAC via the Mastercard Travel Pass app - 4 visits per calendar year, kept active by at least USD 1 of international spend every 3 months.
2-for-1 dining and leisure
Mastercard-provided buy-one-get-one-free offers on dining, premium spas and leisure activities.
Sharia-compliant structure
Commodity Murabaha covered card approved by the bank's Internal Shariah Supervision Committee - the late fee is an 100 donation to charity, waived when you pay on time.
Free supplementary cards
Up to three supplementary cards at no charge, so family spending counts toward the 8,000 monthly tier.
App-first banking
Apply, manage categories and track per-transaction cashback entirely in the Al Hilal app - no branch visit needed.
Pros and cons
- No annual fee, ever - and up to 3 free supplementary cards
- You pick your two 5% categories from grocery, fuel, dining, education and international spend
- Solid 500 monthly cashback ceiling for a free card
- 1% base cashback with no minimum spend to start earning
- Sharia-compliant Murabaha structure with app-based issuance
- The full 5% needs over 8,000 total retail spend in the month - below 3,000 your chosen categories earn just 1%
- Cashback capped at 250 per chosen category ( 500 total) a month
- High 3.14% foreign-currency markup, and EEA purchases earn only 1% even on the international category
- Steep 3.69% monthly profit rate (44.28% p.a.) for new customers if you carry a balance
- Government payments and utility bills paid in the app earn nothing
Is it right for you?
Get this card if
- Your household reliably spends over 8,000 a month on the card
- Your spending concentrates in two of: grocery, fuel, dining, education, international
- You want a Sharia-compliant cashback card with zero annual fee
- You pay your balance in full every month
Consider skipping it if
- You spend under 3,000 a month - you'd earn just 1%
- You spend heavily abroad: the 3.14% FX markup eats most of the 5%, and EEA purchases only earn 1%
- You regularly carry a balance - 3.69% a month is punishing
- You'd max the 500 cap and want uncapped earning
Alternatives to consider
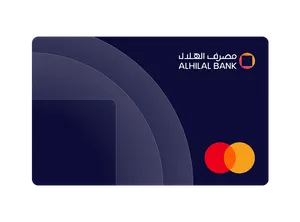
Al Hilal's World Mastercard swaps cashback for TouchPoints - 2.9 per on international and airline spend - plus 8 lounge visits a year.
Best Islamic cards →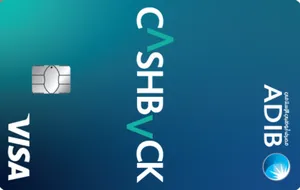
ADIB's Cashback Gold is a competing Sharia-compliant cashback card - compare its flat-rate earning against Al Hilal's tiered 5% categories.
Best cashback cards →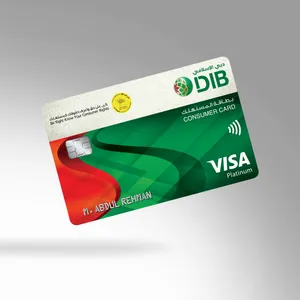
DIB's Consumer Cashback Platinum keeps the Islamic structure with a more straightforward cashback scheme - no monthly spend tiers to track.
Best cashback cards →Not sure which way to go? Put them side by side in our card comparison tool or browse the full ranked list.
Frequently asked questions
Does the Al Hilal Cashback Credit Card have an annual fee?+
No. The annual fee is free, and up to three supplementary cards are also free (AED 105 from the fourth onwards). All charges include VAT.
How does the 5% cashback work?+
You choose two categories from grocery, fuel, dining, education and international spend in the Al Hilal app. In months when your total retail spend exceeds AED 8,000 those categories earn 5%; between AED 3,000 and 8,000 they earn 3%; below AED 3,000 they earn 1%. Everything else earns 1%.
Is there a cap on cashback?+
Yes. Each of your two chosen categories is capped at AED 250 per month, and total cashback is capped at AED 500 per statement cycle.
Can I change my 5% cashback categories?+
Yes, once a month from the Al Hilal app under Manage Card, effective the next calendar month. Changes are free twice per calendar year; further changes cost AED 25.
What earns no cashback?+
Government-type payments (tolls, fines, court costs, tax, postal services, local transport) and utility bill payments made through the Al Hilal app earn 0%. Balance transfers, instant cash and cash withdrawals never earn cashback, and you must pay at least your minimum due to stay eligible.
When is cashback paid out?+
The total cashback for a month is credited to your credit card account as one transaction on or before the 15th of the following month.
Is the card Sharia compliant?+
Yes. It is a covered card operating under a commodity Murabaha structure, approved by Al Hilal Bank's Internal Shariah Supervision Committee, with the certificate published on the bank's website.
Does the card include airport lounge access?+
Yes - access to 25+ lounges via the Mastercard Travel Pass app, capped at 4 visits per calendar year. You need at least USD 1 of international spend on the card every 3 months to keep the benefit active.
Editorial disclaimer: Opinions expressed here are the author’s alone, not those of any bank or card issuer, and have not been reviewed, approved or otherwise endorsed by any of these entities.