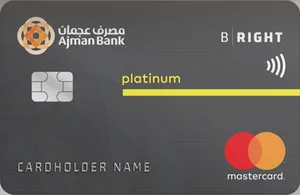
Ajman Bank BRight Platinum Credit Card
10,000 BRight Rewards upfront + 0% foreign transaction fees
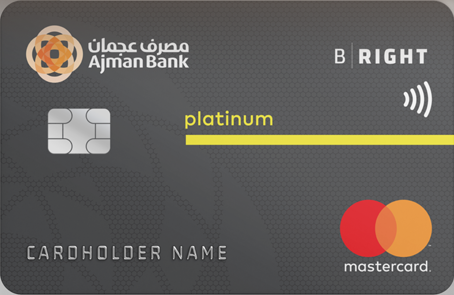
at Ajman Bank's secure site
See rates & fees.
Rewards rate
This is the BRight World's value play: the 0% FX markup and lounge access survive the 500 price cut, and only the earn rate and upfront points shrink. If you pay in full and mostly want cheap foreign spending, the Platinum is arguably the smarter buy — but the bank's silence on salary requirements and lounge terms applies here too.
Earning and redeeming BRight Rewards
The BRight Platinum earns up to 1.5 BRight Rewards for every 10 you spend. The bank's own 'up to' phrasing suggests not every category earns the full rate, and no category table is published, so treat 1.5 as the ceiling rather than a guarantee.
Redemption runs through www.ajmanrewards.ae: flight bookings across 300+ airlines, more than 300,000 hotel options, gift vouchers and electronics. The bank does not publish a per-point value or an expiry policy, so test redemption prices before you stockpile points.
Rates and fees
- Annual fee
- 1,000 per year, exclusive of 5% VAT. No advertised first-year waiver.
- Foreign transaction fee
- 0% bank processing fee — Mastercard's standard scheme fee on international transactions still applies.
- Profit rate (Murabaha)
- Fixed 42% per annum (~3.5% per month) when the balance isn't paid in full by the due date.
- Cash advance fee
- 150 per transaction (per withdrawal up to 5,000).
- Late payment
- 125 commitment-to-donation — routed to charity under Sharia supervision, net of the bank's actual costs.
- Supplementary cards
- First 2 free, then 50 per card per year.
- Balance transfer / Easy Cash
- 0.99%–1.5% per month depending on tenure, up to 36 months.
Figures from Ajman Bank's Credit Card Key Facts Statement (May 2025). All fees exclusive of 5% VAT. Verify with the bank before applying.
Card benefits
0% foreign transaction fees
No bank markup on overseas or foreign-currency spend — only Mastercard's own scheme fee applies. The same headline perk as the pricier BRight World.
10,000 BRight Rewards upfront
Granted as a complimentary welcome boost so you can 'plan your trip instantly', per the bank — redeemable at ajmanrewards.ae.
Airport lounge access
Complimentary lounge access is advertised, though the bank publishes no program name or visit limits — confirm details before you travel.
Valet parking, 3x a month
Complimentary valet at over 35 locations across the UAE, three times every month.
Up to 30% off Cleartrip
Discounted flight and hotel bookings through Cleartrip when paying with the card.
Sharia-compliant structure
Murabaha-based card from a fully Sharia-compliant bank; late-payment amounts are donated to charity under the Internal Shariah Supervision Committee.
Pros and cons
- 0% bank markup on foreign-currency spend — same as the pricier BRight World
- 10,000 BRight Rewards granted upfront, no spend hoop advertised
- Complimentary lounge access at a mid-tier annual fee
- Valet parking 3 times a month at 35+ locations
- Late payment charge ( 125) goes to charity under Sharia supervision, not to the bank
- 1,000 annual fee (plus 5% VAT) with no advertised first-year waiver
- Earn rate drops to 1.5 per 10 — 40% less than the BRight World
- Mastercard's own scheme fee still applies to international transactions despite the 0% bank markup
- Murabaha profit is a steep 42% per annum if you don't pay in full
- No published minimum salary, lounge program details or points-expiry terms
Is it right for you?
Get this card if
- You want 0% foreign transaction fees without paying the World's 1,500
- You value lounge access and valet more than fast points accumulation
- You want a Sharia-compliant travel card from a fully Islamic bank
- You pay your balance in full every month
Consider skipping it if
- You spend enough to justify the World's 2.5x earn rate and 15,000 points
- You want published lounge terms and salary requirements before committing
- You ever carry a balance — 42% p.a. profit is punishing
- You'd rather have simple cashback than a bank points program
Alternatives to consider
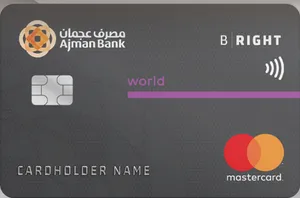
For 500 more a year, the BRight World lifts earning to 2.5 points per 10, grants 15,000 upfront points and adds a fourth monthly valet visit.
Best travel cards →
The BRight Titanium is free for life and keeps you in the same BRight Rewards program — you give up the 0% FX fee, lounge access and the upfront points.
Best no-annual-fee cards →
Ajman Bank's ULTRACASH pays up to 10% cashback on two everyday categories you pick — fuel, online, supermarkets or school fees — instead of travel points.
Best cashback cards →Not sure which way to go? Put them side by side in our card comparison tool or browse the full ranked list.
Frequently asked questions
What is the annual fee for the Ajman Bank BRight Platinum card?+
AED 1,000 per year, excluding 5% VAT. The bank does not advertise a first-year waiver. Supplementary cards: the first 2 are free, then AED 50 per card per year.
Does the BRight Platinum card charge foreign transaction fees?+
Ajman Bank charges 0% processing fee on foreign-currency transactions for this card. However, the standard scheme fee charged by Mastercard on international transactions still applies, so overseas purchases are not entirely fee-free.
Is the BRight Platinum card Sharia-compliant?+
Yes. It is structured under the Islamic principle of Murabaha, and Ajman Bank is a fully Sharia-compliant bank. Late payments incur an AED 125 commitment-to-donation amount that goes to charity under the bank's Internal Shariah Supervision Committee.
How many BRight Rewards does the Platinum card earn?+
Up to 1.5 BRight Rewards for every AED 10 spent, redeemable at www.ajmanrewards.ae across 300+ airlines, 300,000+ hotels, gift vouchers and electronics.
What welcome bonus does the BRight Platinum offer?+
The bank advertises 10,000 complimentary BRight Rewards granted upfront under its 'plan your trip instantly' pitch. No spend requirement is published, but confirm the conditions with the bank when applying.
What is the profit rate if I carry a balance?+
The Murabaha profit rate is a fixed 42% per annum (about 3.5% per month), applied when you do not pay the total outstanding in full by the due date.
Editorial disclaimer: Opinions expressed here are the author’s alone, not those of any bank or card issuer, and have not been reviewed, approved or otherwise endorsed by any of these entities.