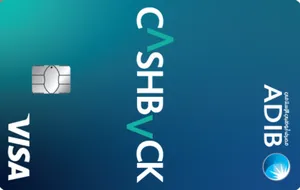
ADIB Cashback Gold
4% cashback on your everyday essentials
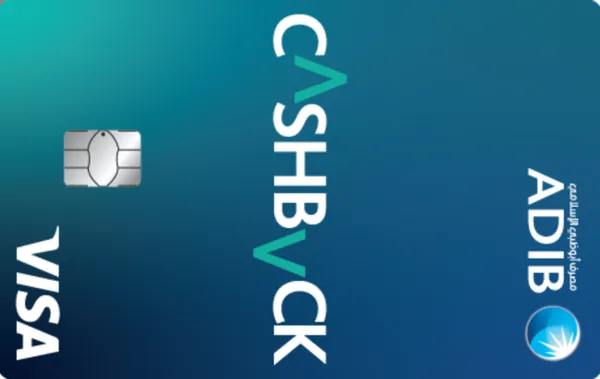
at ADIB's secure site
Terms & conditions apply. See rates & fees.
Cashback rate
"At 99 a year, this is the rare cashback card where the fee is basically irrelevant — one average grocery month pays for it. Treat it as a category card: 4% on groceries, fuel, school fees, dining and bills, and keep a second card for everything else, because ADIB publishes no earn rate beyond those five categories."
Earning cashback on the ADIB Cashback card
The card pays a flat 4% cashback on five everyday categories — supermarkets and groceries, fuel and automobile, school and education payments, dining, and utility bills. Each category carries its own monthly cashback ceiling: 300 for groceries, fuel and education, 200 for dining and 100 for utilities, with an overall cap of 1,000 a month.
Work the caps backwards and the sweet spot becomes clear: at 4%, the grocery cap covers 7,500 of monthly spend, dining 5,000 and utilities 2,500. Spend beyond that — or outside the five categories entirely — and ADIB publishes no cashback rate at all, so route general spending through another card. Note the bank flags every category benefit as discretionary and changeable after notice.
Rates and fees
- Annual fee
- 99 (plus 5% VAT); no first-year waiver advertised
- Monthly profit rate
- 3.75% fixed (45.63% APR) Murabaha profit, calculated on the full cover limit and waived fully or partially via investment profit and a discretionary bank bonus when you pay on time
- Grace period
- Up to 55 days from the transaction date when the balance is paid in full
- Cash withdrawal
- Up to 100% of the cover limit; fee of 3% of the amount (minimum 99)
- Late payment
- 100 donation commitment to charity (no VAT); missed payments are reported to the credit bureau
- Minimum monthly payment
- 5% of the outstanding amount, minimum 100
- Supplementary cards
- Four free; 99 a year from the fifth card
- Minimum salary
- Not published for this card — the Central Bank covered-card floor is 5,000/month
- Card network
- Visa (Gold)
Rates verified against the ADIB Covered Cards Key Facts Statement (V14-A, April 2026) and adib.ae on August 21, 2026. Fees exclude 5% VAT unless stated. Always confirm on ADIB's site before applying.
Card benefits
4% on five categories
Groceries, fuel and automobile, school and education, dining, and utilities all pay 4% cashback, each with its own monthly cap.
Roadside assistance
Free roadside assistance once a year — a rare extra on a sub- 100 card.
Four free supplementary cards
Add up to four family cards at no charge; a fifth costs 99 a year.
Full limit as cash
Withdraw up to 100% of your finance limit as cash (3% fee, minimum 99).
Pros and cons
- Flat 4% cashback across five everyday spend categories
- Very low 99 annual fee (plus VAT)
- Grace period of up to 55 days when you pay in full
- Four free supplementary cards
- Withdraw up to 100% of your cover limit as cash
- Per-category cashback caps are tight — 100 to 300 each
- No published cashback rate on spend outside the five categories
- No lounge access or travel perks
- Cashback categories are at the bank's discretion and can change after notice
- 3.75% monthly Murabaha profit rate applies if you don't clear your balance
Is it right for you?
Get this card if
- Your monthly spend is dominated by groceries, fuel, school fees, dining and utility bills.
- You want Sharia-compliant cashback with a fee small enough to ignore.
- You're happy running a second card for general and international spend.
Consider skipping it if
- You spend far past the caps — 300 per category vanishes quickly at 4%.
- You want cashback on everything you buy, not just five categories.
- You expect travel perks — there's no lounge access or travel insurance here.
Alternatives to consider
ADIB's Smiles Classic is free for life, with 5,000 welcome Smiles points and quarterly bonus points instead of cashback.
Best no-annual-fee cards →
The Emirates NBD noon One card rewards noon, noon Food and noon Minutes orders — stronger if delivery apps outweigh the petrol station in your budget.
Best online shopping cards →
ADIB's Booking.com Signature adds unlimited lounge access, travel cover and Exceed Rewards for 299 a year.
Best travel cards →Not sure which way to go? Put them side by side in our card comparison tool or browse the full ranked list.
Frequently asked questions
How much cashback does the ADIB Cashback card pay?+
A flat 4% on five categories: supermarkets and groceries, fuel and automobile, school and education payments, dining, and utility bills. Each category has its own monthly cashback cap (AED 300 for groceries, fuel and education; AED 200 for dining; AED 100 for utilities), and total cashback is capped at AED 1,000 a month.
What is the annual fee on the ADIB Cashback card?+
AED 99 a year (plus 5% VAT), per the ADIB Covered Cards Key Facts Statement. Supplementary cards are free up to four; a fifth card costs AED 99 a year.
Is the ADIB Cashback card Sharia-compliant?+
Yes. It's a covered card from Abu Dhabi Islamic Bank, structured as a commodity Murabaha rather than an interest-bearing credit card. A fixed 3.75% monthly Murabaha profit is calculated on the cover limit, but ADIB waives it fully or partially — via short-term investment profit and a discretionary bank bonus — when you make your payments on time.
What salary do I need to qualify?+
ADIB doesn't publish a card-specific minimum salary for this card. The Key Facts Statement notes the UAE Central Bank's general covered-card eligibility floor of AED 5,000 monthly income — confirm your eligibility with ADIB before applying.
Do purchases outside the five categories earn cashback?+
ADIB doesn't publish any base cashback rate for other spend, so treat purchases outside groceries, fuel, education, dining and utilities as earning nothing.
Does the card come with any extras?+
Free roadside assistance once a year, four free supplementary cards, the ability to withdraw 100% of your cover limit as cash, and an ongoing feature that splits school and university fees into monthly instalments.
Editorial disclaimer: Opinions expressed here are the author’s alone, not those of any bank or card issuer, and have not been reviewed, approved or otherwise endorsed by any of these entities.